Does IRS collection stop during an appeal? A timely CDP request generally pauses levy; other appeals may not
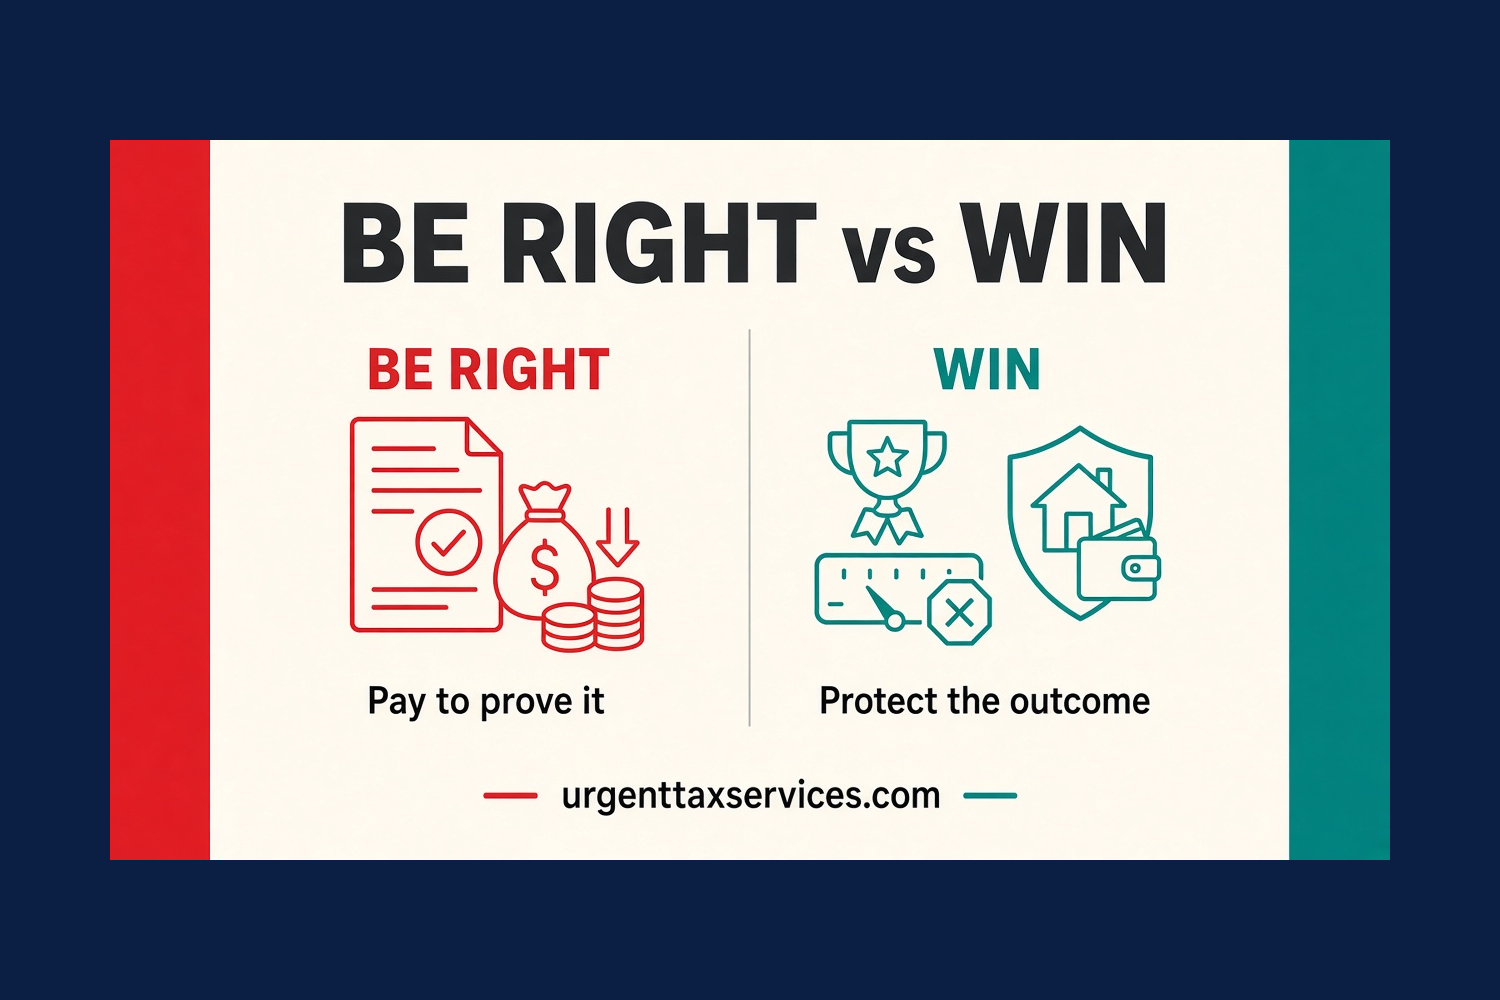
Would you rather be right with the tax authorities, or win your case?
So does IRS collection stop during an appeal? Not always.
A lot of taxpayers run into this. While you're negotiating with the IRS or a state tax department, or while your case sits with an appeals office or a court, collections can keep moving. Not every collection employee knows every collection rule. And sometimes the appeals side never tells the collection side to hold off.
A recent case
I recently filed a case for a client with a state division of tax appeals. The judge assigned to the case had been inactive for several months. While the case was pending, nobody told state collections to stop.
My client had a real dilemma. Pay money, penalties and interest he didn't think he owed. Or hope the judge came back and issued an order to stop collection in time.
I quickly filed with a different state department for a hearing and to stop collection. He was lucky. The judge did return to work in time.
But luck is not a strategy.
Being right doesn’t stop the knot in your stomach every time the mail comes. While a case sits waiting, people wonder if this is the letter that freezes their bank account. That worry is part of the cost, even when you win.
Why IRS collection doesn't always stop during an appeal
Appeals, audits and collections are often different offices with different staff and different systems. A pending dispute in one place doesn't automatically freeze everything in another. Notices keep printing. Interest keeps adding up. And in some situations, a levy can still go out.
Collection Due Process and other protections, if you use them
On the IRS side, a few rules help:
Collection Due Process (CDP). When you get a Final Notice of Intent to Levy (often an LT11 or Letter 1058), you generally have 30 days to request a CDP hearing. A timely request generally stops levy action while the hearing is pending. Miss the 30 days and you can still ask for an "equivalent hearing" within a year, but levies may continue during it.
Collection Appeals Program (CAP). You can appeal certain collection actions, before or after a levy.
Tax Court in a deficiency case. While a timely Tax Court petition on a proposed assessment is pending, the IRS generally can't assess that tax or levy to collect it.
Pending requests. While a proper installment agreement request or Offer in Compromise is pending, the IRS generally isn't allowed to levy.
The catch: almost every one of these depends on a deadline, the right form and the right office. That's where people get hurt.
States have their own rules and procedures. They don't always match the IRS. That was exactly my client's problem.
Fight smart, not just hard
Here's how I think about it. When two people fight and each wants to hurt the other more, the one who stops after the first hit may not "sound right." But he avoids getting hit again and again just to land the last punch.
Sometimes paying part of a disputed amount, or setting up a temporary arrangement, protects you from levies, extra penalties and a frozen account while the dispute plays out. If you win, you may be able to get money back. If you refuse on principle, you might be right and still lose more than the tax itself.
We have to remember what the target is: winning. Not just being right.
What I do in these cases
Find every open office on your case: audit, appeals, collections, state and federal.
Check which protections apply and which deadlines are still open.
File the right requests so collection is paused where the law allows.
When it makes sense, use a short-term arrangement to protect your accounts while the appeal is decided.
FAQ
Does filing an appeal stop IRS collection?
It depends on the type of appeal. A timely CDP request generally stops levy. Other appeals may not stop everything, so check each one.
What if I missed the 30-day CDP deadline?
You may be able to request an equivalent hearing within one year, but levy action may continue while it's pending.
Should I pay a tax I'm disputing?
Sometimes paying part, or setting up a plan, protects you while you fight. It depends on your case and the rules for getting money back.
Do state appeals work the same as IRS appeals?
No. Each state has its own procedures and deadlines.
What is a Collection Due Process hearing?
A hearing with IRS Appeals that you request after a final notice of intent to levy, generally within 30 days of the notice. A timely request generally stops levy while it's pending.
Related: CP504 vs. LT11 · IRS Appeals vs. Tax Court burden of proof · IRS bank levy help
Official sources: IRS: Collection Due Process FAQs · IRS Independent Office of Appeals · IRS: Understanding your LT11 notice or Letter 1058
Sitting on a notice right now?
Book a free consultation to go over your case. I'll tell you straight where you stand.
Every case is different.
Solomon Grosinger, Enrolled Agent
I'm licensed by the IRS and have represented taxpayers before the IRS and New York, New Jersey, Connecticut and Pennsylvania tax agencies from Brooklyn since 2017.
General info, not advice for your specific case.