IRS payment plan vs. loan: interest and penalties on an installment agreement compared with the cost of a loan
A client recently asked me why he should take out a loan to pay the IRS instead of just setting up an installment agreement.
It's the IRS payment plan vs. loan question, and the answer comes down to cost and risk.
It's a fair question. Here's what I told him.
An IRS payment plan isn't free
An installment agreement doesn't freeze the cost of the debt. While you're on the plan, you still pay:
IRS interest. For the fourth quarter of 2026, it's 7% a year for individuals, compounded daily. The rate can change every quarter.
The failure-to-pay penalty. For an individual who filed on time and has an approved plan, it's 0.25% a month. If you didn't file on time, it's generally 0.5% a month.
A setup fee. Depending on how you apply and how you pay, the IRS charges from $29 to $178 (lower or waived for low-income taxpayers).
A simple example
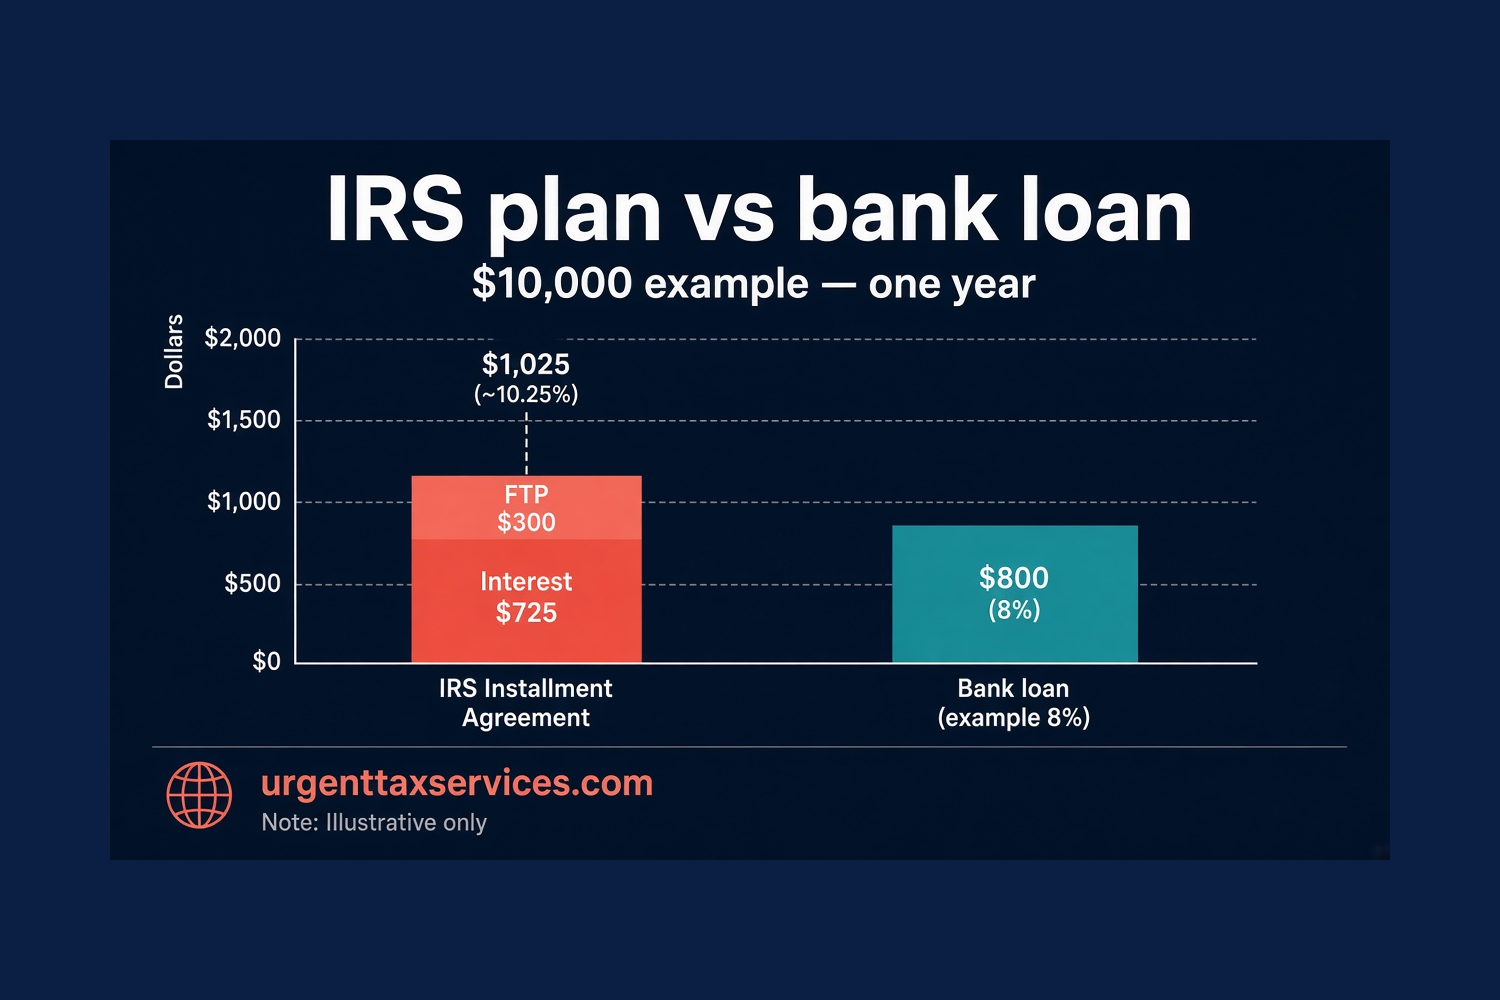
Say you owe $10,000. If nothing else changed for a year:
interest would be roughly $725,
the failure-to-pay penalty would be about $300.
That's about $1,025, or a little over 10%, before the setup fee.
In real life, the cost goes down as you pay the balance down. But the point stands: the IRS is charging you for the time.
A payment plan isn't automatic
An installment agreement is also not automatic. On larger balances, above the IRS's simple payment plan limits, the IRS looks at what you own. If you or your business have enough assets to cover the debt, the IRS can deny the payment plan and expect you to use those assets first.
What happens if you fall behind
And if you default on an installment agreement, the IRS can end it and demand the full balance, with levies back on the table. A bank, on the other hand, might work with you if you fall behind.
A bank and the IRS are not the same kind of lender
In my opinion, there is a major difference between a bank and the IRS. A bank's main business is lending money, and it does so willingly. The IRS only agrees to wait for its money when it has to, because the taxpayer can't pay right now.
IRS payment plan vs. loan: how a loan compares
A bank loan is different. If you use it to pay the IRS in full, the IRS interest and penalty stop on what you paid. Your cost becomes whatever the bank charges.
So:
If the loan is cheaper than the IRS stack, the loan can make more sense.
If you can't get a loan, or the rate is worse, the installment agreement is still the way to pay over time without enforced collection hanging over you.
It's not that one is always better. It's that an IRS payment plan is not free, and not guaranteed. People treat it like it is.
I know what a payment plan feels like from the other side of the desk. It feels like relief. Finally, the letters stop and you can breathe. But every month the interest keeps growing quietly in the background. I’d rather you sleep well because the numbers actually work, not because you stopped opening the mail.
Things to watch with a loan
Don't put your home at risk lightly. A secured loan you can't repay can be worse than an IRS plan.
Credit cards are usually expensive. Compare the real rate, plus any card processing fees.
Business owners: paying off the IRS with a loan won't fix a cash-flow problem that keeps creating new tax debt.
IRS installment agreement rules to know
Simple Payment Plans. Individuals who owe $50,000 or less in assessed tax, penalties and interest, and have filed all required returns, can generally get a plan without a financial statement. Above that, expect the IRS to ask about your income, expenses and assets.
Collection generally pauses. The IRS generally won't levy while a payment plan request is being considered or while the plan is in effect.
Refunds go to the debt. Future refunds are applied to your balance until it's paid.
The lien doesn't disappear. A payment plan doesn't remove a federal tax lien by itself. In some cases, a direct debit plan can help you get the public lien notice withdrawn.
Stay current. Missing payments, unfiled returns or new balances can default the plan. If the IRS ends it, the full balance is due again and enforced collection can start after the 30-day window.
How I help you decide
I look at your full picture: what you owe, the IRS rate right now, the loan you can actually get, your cash flow and whether there's a lien in the way of financing. Then I tell you which path I think costs less and is safer for you.
FAQ
Does the IRS charge interest on payment plans?
Yes. Interest keeps running, plus a failure-to-pay penalty. For individuals who filed on time, that penalty is 0.25% a month during an approved plan.
Is it smart to take a loan to pay the IRS?
Sometimes. If the loan's total cost is lower than IRS interest plus penalties, it can be. Compare carefully, and don't risk your home lightly.
Can the IRS turn down a payment plan?
Yes. On larger balances the IRS reviews your finances, and if you have assets that could pay the debt, it can deny the plan and expect you to use them first.
Will a payment plan stop a levy?
Generally, the IRS won't levy while a plan request is pending or while the plan is in effect.
How much does an IRS payment plan cost to set up?
From $29 to $178 depending on how you apply and pay, with reduced or waived fees for low-income taxpayers.
Related: File even if you can't pay · Offer in compromise: what it takes · IRS lien vs. levy
Official sources: IRS: Payment plans (installment agreements) · IRS: Interest · IRS: Failure to pay penalty
Trying to decide?
Free consultation: book a time and I'll run the comparison with you. I help with IRS, New York, New Jersey, Connecticut and Pennsylvania tax problems.
Solomon Grosinger, Enrolled Agent
I'm licensed by the IRS and have represented taxpayers before the IRS and New York, New Jersey, Connecticut and Pennsylvania tax agencies from Brooklyn since 2017.
General info, not advice for your specific case.