1120-S late filing penalty: charged per shareholder, per month, even when the S corporation owes no tax
A client got hit with a $410 penalty for filing his 1120-S two months late.
That's the 1120-S late filing penalty, and it applies even when the S corp owes no tax.
There was no tax due on the return. So he didn't understand why the IRS was charging a penalty at all.
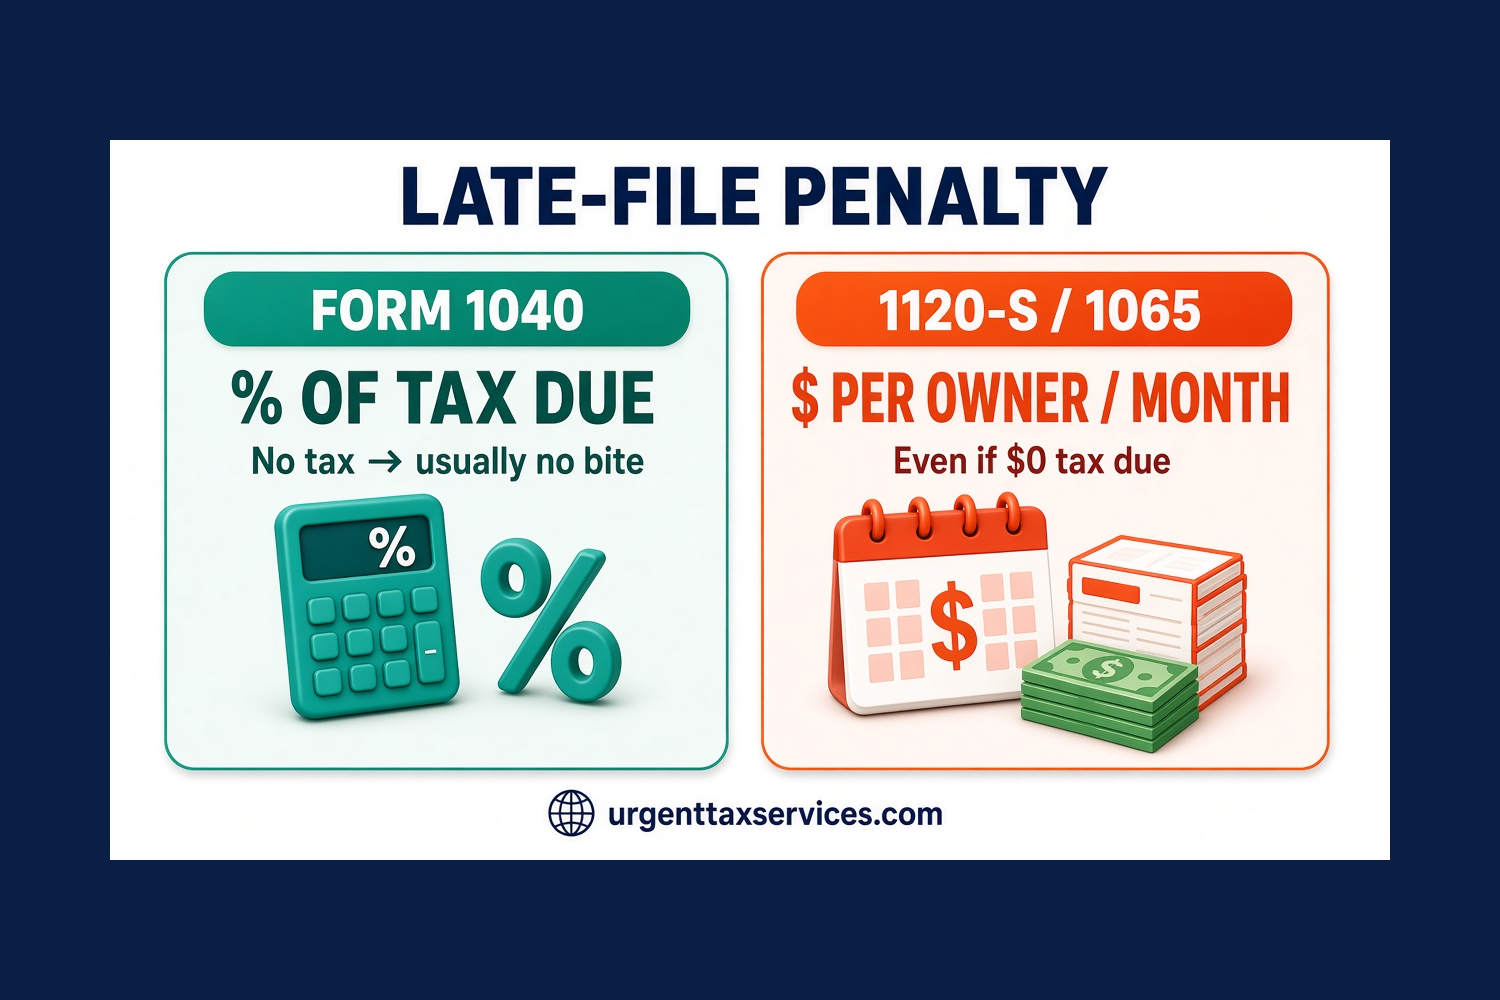
His thinking made sense on the surface. On a late personal return (Form 1040), the failure-to-file penalty is usually a percentage of the unpaid tax. So if nothing is owed, people assume there's no late-filing penalty either.
I had to explain that the S-corp return doesn't work that way.
How the 1120-S late-filing penalty works
The late-filing penalty for an S corporation return isn't based on tax due. It's a flat monthly charge under Internal Revenue Code section 6699. It's figured:
per shareholder,
per month or part of a month the return is late,
for up to 12 months.
A zero balance on the S-corp return doesn't turn the meter off. Partnerships filing Form 1065 work the same way under a parallel rule.
The dollar amount per shareholder is set by law and adjusted for inflation, so it goes up over time. For recent years, it has been more than $200 per shareholder, per month.
Why there's usually no tax on the return
This is the part that confuses business owners.
Even very profitable companies, ones whose owners pay a lot of tax, usually don't send any payment with an 1120-S or 1065. These are mostly informational returns. The income flows through to the owners' personal returns, and the owners pay the tax there. There are some unique situations where the entity itself owes tax, but they're the exception.
The IRS still wants the form on time. It's how the IRS matches the income on each owner's personal return.
Do the math
One shareholder. Two months late. $410. No tax due on the 1120-S. Still a penalty.
Now picture three or four shareholders and a return that's six months late. That meter multiplies fast.
How to avoid it: the 1120-S due date and Form 7004
Know the deadline. For a calendar-year S corporation, the 1120-S is generally due March 15. That's a month earlier than most personal returns.
File an extension if you need time. A timely extension (Form 7004) generally gives you six more months to file.
Don't wait on the owners' personal returns. The S-corp return usually has to go in first, since the owners need their K-1s.
Already got the penalty? First-time penalty abatement
Don't just pay it without looking. Depending on the facts, it may be possible to ask the IRS to remove it:
Reasonable cause. If something outside your control kept you from filing on time, like a serious illness or a disaster, and you acted responsibly, you can explain that to the IRS.
First-time relief. If the company has a clean recent history, an administrative first-time abatement may apply.
Each request depends on the facts. I'll tell you honestly if I think there's a basis.
FAQ
Why did I get a penalty if my S corporation owed no tax?
Because the 1120-S late-filing penalty is a flat amount per shareholder per month, not a percentage of tax due.
Does the same rule apply to partnerships?
Yes. Form 1065 has a parallel per-partner, per-month late-filing penalty.
When is a calendar-year 1120-S due?
Generally March 15, with a six-month extension available if filed on time.
Can the penalty be removed?
Sometimes, through reasonable cause or first-time abatement. It depends on your facts.
Does a Form 7004 extension avoid the penalty?
Yes, if it's filed by the original due date. Then the return is on time if it's filed by the extended due date. If the Form 7004 never went in, a September return is late.
Related: Is your tax extension valid? · NY, NJ & CT tax penalty abatement · S corp and partnership return errors
Official sources: IRS: About Form 1120-S · IRS: About Form 7004 · IRS: Administrative penalty relief (first-time abate)
Got a penalty notice?
Send me the notice and I'll tell you plainly where you stand, including whether I think there's a real basis to ask for relief. I help with S corp and partnership penalties and other tax problems with the IRS, New York, New Jersey, Connecticut and Pennsylvania.
Solomon Grosinger, Enrolled Agent
I'm licensed by the IRS and have represented taxpayers before the IRS and New York, New Jersey, Connecticut and Pennsylvania tax agencies from Brooklyn since 2017.
General info, not advice for your specific case.