Burden of proof IRS: the four section 7491 hurdles of credible evidence, substantiation, records and cooperation
A potential client called me after an audit went sideways.
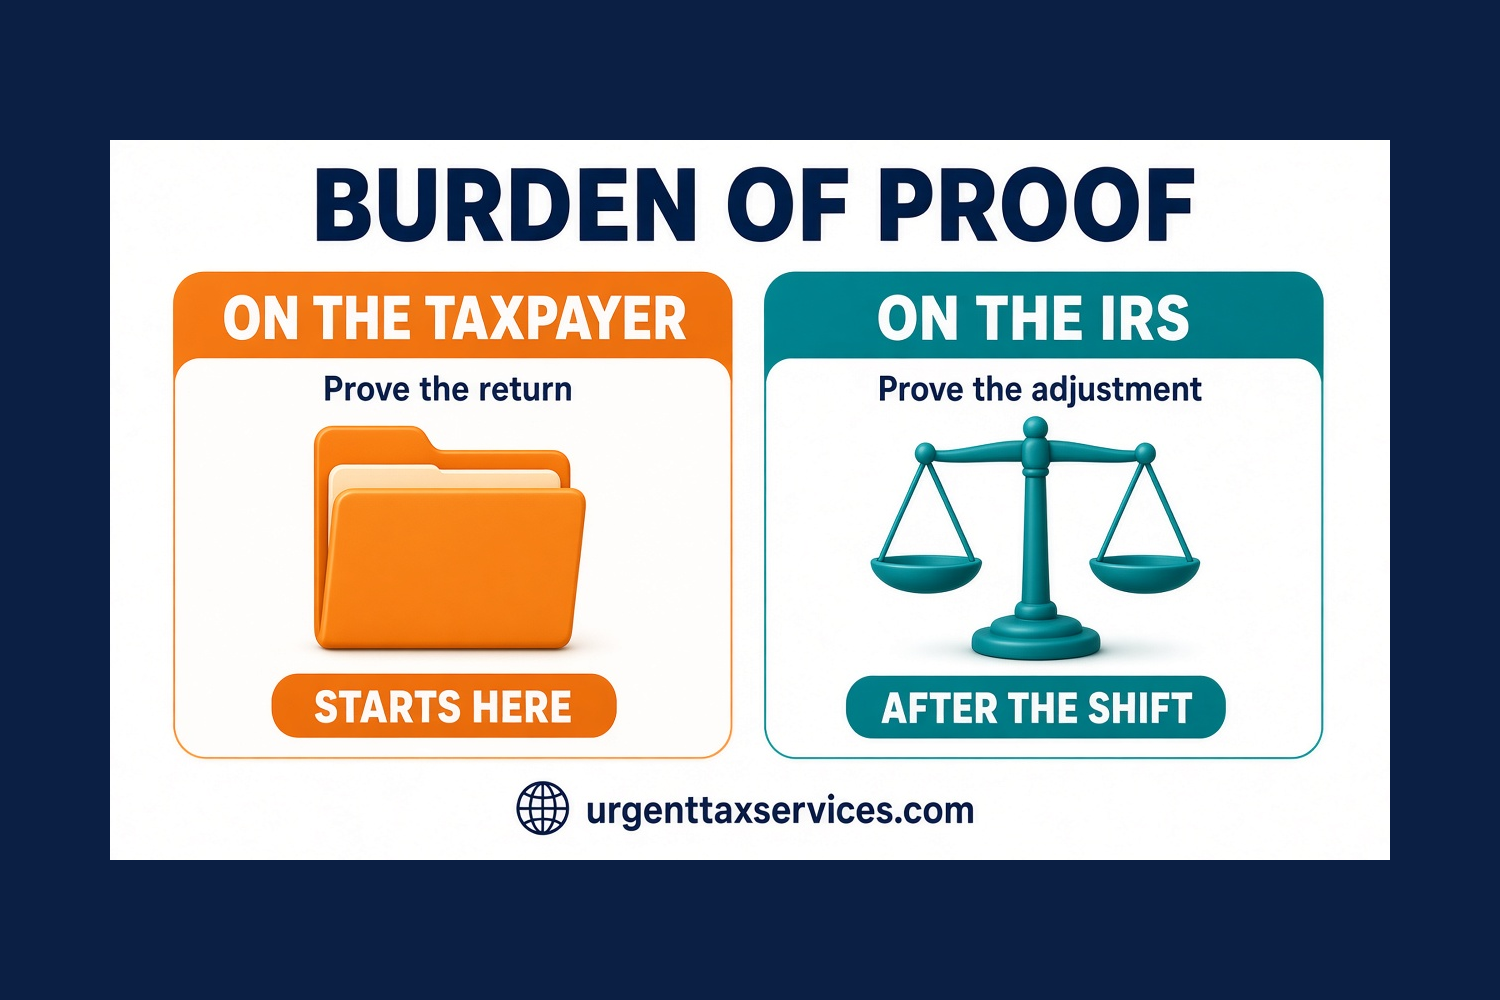
Under section 7491, the burden of proof can shift to the IRS, but only in narrow cases.
The business was real. The revenue was real. The books were a mess. Bank deposits in one place, expenses in another, half the year in a shoebox, the other half "I'll get it to you next week."
He'd heard that in Tax Court you can shift the burden of proof to the IRS. So in his mind, once he got there, the IRS would have to prove he was wrong.
I had to be straight with him.
What section 7491 says about the burden of proof
Under Internal Revenue Code section 7491, you can put the burden of proof on the IRS for a factual issue. But only if you've already cleared four hurdles. Messy books don't clear them. They trip over them.
Here's how I walked him through it.
Hurdle 1: Credible evidence
A judge needs something solid to base a finding on, if the IRS doesn't knock it down. Contracts. Bank records. Real valuations. Not reconstructed guesses, and not "I think that was inventory."
If your file can't support the number, you don't get the shift on that number.
Hurdle 2: Substantiate the way the law requires
Some expenses, like travel, meals and car use, have strict substantiation rules. That means records kept at the time, not a spreadsheet you built the night before the meeting.
If you can't document the expense the way the rules require, that item doesn't ride on a burden shift later.
Hurdle 3: Keep the IRS audit records the law requires
This was his wall.
When you don't keep basic books and receipts, the IRS can reconstruct your income its own way, using bank deposits, industry averages or whatever method fits. You're not in a position to demand that the IRS carry the burden when you never kept a usable set of books.
Hurdle 4: Cooperate with reasonable IRS requests
During the exam, the IRS asks for documents, interviews and meetings. Respond. If you stonewall because you're scrambling to invent records you should have had, you've already given away the courtroom advantage.
(For businesses, there's also a size limit. Larger entities can't use this rule at all.)
What I told him
I told him we weren't going to sell a section 7491 fantasy on top of a shoebox.
Instead, the plan was to fix the recordkeeping, fight with what he could actually prove, and stop counting on a courtroom rule that rewards the taxpayer who did the boring work years earlier.
The burden shift isn't for the messy file. It's for the file that was already in order before anyone said "petition."
What this means for you
If you're in an audit now:
Gather what's real. Bank statements, invoices, contracts, canceled checks. These carry weight.
Don't invent records. Recreated logs that look new usually hurt more than they help.
Answer IRS requests on time. Cooperation matters, both for the audit and for any later dispute.
Get help early. It's much easier to shape an audit than to fix it after a bad report.
And if you're not in an audit, this is your sign to clean up the books now.
FAQ
Can I make the IRS prove its case in Tax Court?
Sometimes, on specific factual issues, if you meet the conditions in section 7491. You need credible evidence, proper substantiation, required records and cooperation with the IRS.
What if my records are incomplete?
You can still fight with what you can prove. But don't count on shifting the burden to the IRS.
Should I rebuild my records before the audit meeting?
Organize real documents, yes. Don't create "new" logs that pretend to be from the past.
Do you handle audits?
Yes. As an Enrolled Agent, I can represent you in IRS audits and appeals.
Who has the burden of proof in an IRS audit?
Generally you do. The IRS's numbers are presumed correct. Section 7491 can shift the burden on specific factual issues, but only if you meet all four conditions.
Related: IRS Appeals vs. Tax Court burden of proof · Hobby loss audit · Tax deduction records cases (when live) · Lowering your taxes is legal. A sham real estate deal isn't. · Audited over a low S corp salary? Here’s what’s going on. · The IRS needs a boss’s signature before it can penalize you
Official sources: IRS Internal Revenue Manual 4.10.7 (burden of proof) · IRS: IRS audits
In an audit, or worried about one?
Book a free consultation to go over your case. I'll tell you straight where you stand.
Every case is different.
Solomon Grosinger, Enrolled Agent
I'm licensed by the IRS and have represented taxpayers before the IRS and New York, New Jersey, Connecticut and Pennsylvania tax agencies from Brooklyn since 2017.
General info, not advice for your specific case.