File taxes even if you can’t pay: the failure-to-file penalty compared with the smaller failure-to-pay penalty
A client owed the IRS $10,000.
If you can't pay your taxes, file anyway.
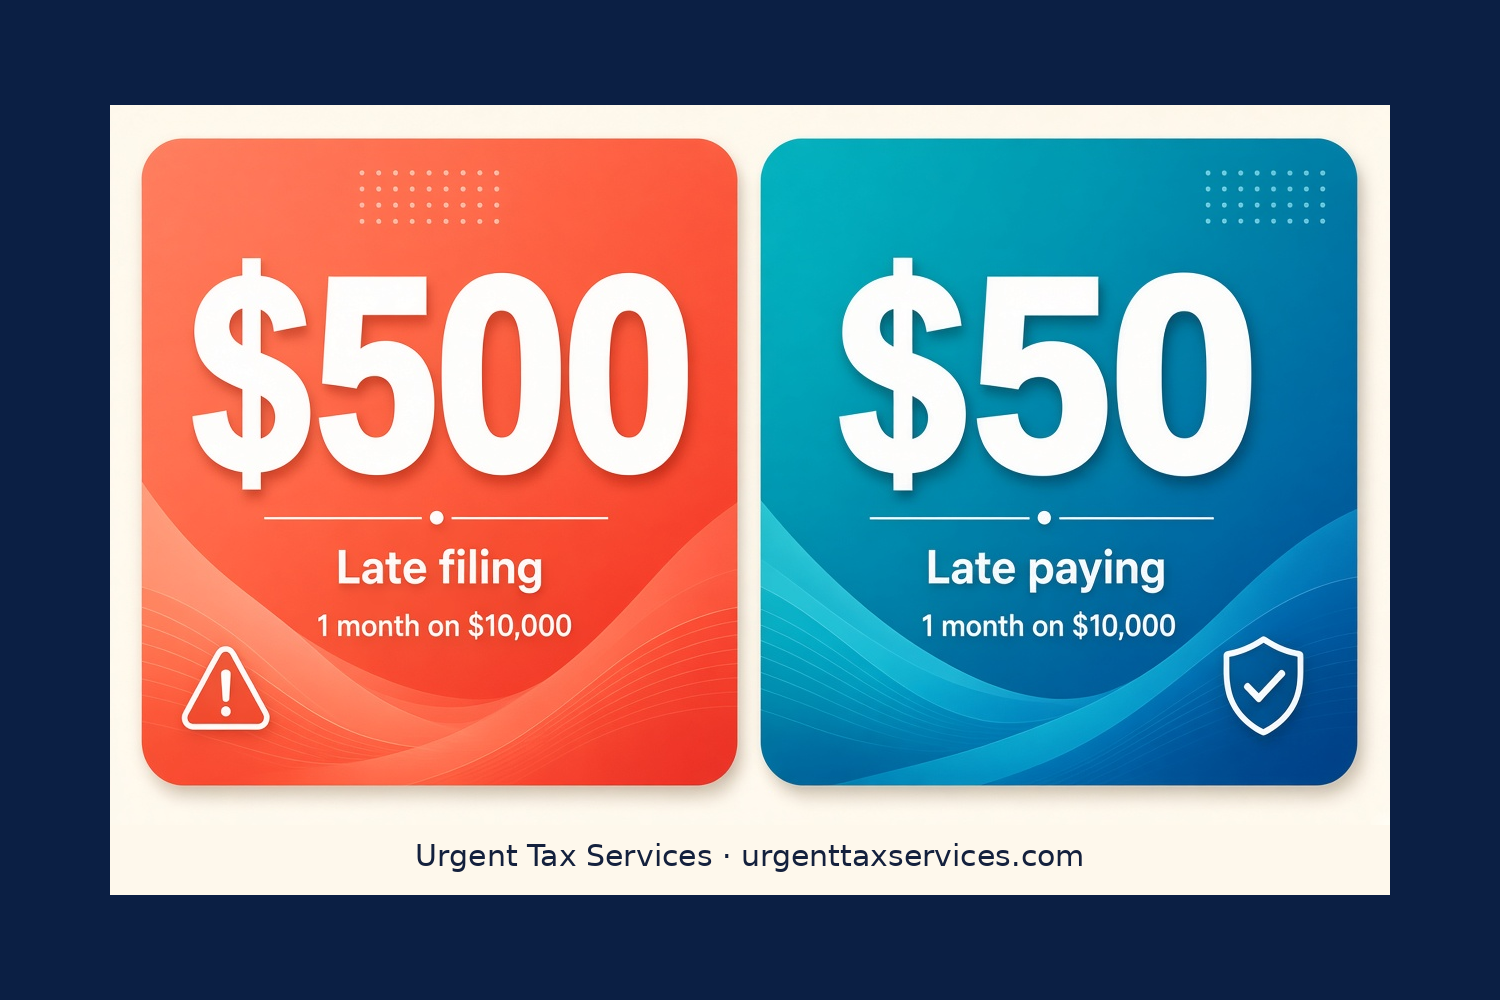
On that example, filing the return late cost about $500 in penalty for the month. Filing on time but not paying cost about $50.
Same balance. Completely different bill.
So here's my advice, and it's the same every time: file even if you can't pay. Waiting doesn't soften anything. It stacks the worse penalty on top of what you already owe.
The failure to file penalty vs. the failure to pay penalty
Failure to file. Generally 5% of the unpaid tax for each month or part of a month the return is late, up to 25%.
Failure to pay. Generally 0.5% of the unpaid tax for each month or part of a month it stays unpaid, also up to 25%.
That's a 10-to-1 difference. On $10,000, one month late on filing is about $500. One month late on paying is about $50.
When both apply in the same month, the IRS reduces the filing penalty by the payment penalty: 4.5% plus 0.5% instead of 5% plus 0.5%. The filing penalty maxes out after five months. The payment penalty keeps going.
There's also a minimum. If your return is more than 60 days late, the failure-to-file penalty is at least $525 (for returns due after December 31, 2025) or 100% of the unpaid tax, whichever is less.
The payment penalty can go up or down
Down: If you filed on time as an individual and you're on an approved IRS payment plan, the failure-to-pay penalty drops to 0.25% a month.
Up: If you don't pay within 10 days after a notice of intent to levy, it goes up to 1% a month.
And interest is charged on top of the tax, and on the penalties too.
Why people don't file
Almost always, it's fear. "If I file, they'll know I owe, and they'll come after me." But the IRS often already knows about your income from W-2s and 1099s. If you don't file, the IRS can prepare a substitute return for you, usually without the deductions you'd claim, and send you a bigger bill anyway.
Filing puts you back in control of the number.
After you file: dealing with the balance
Once the return is in, we can work on the balance with whatever your numbers support:
a short-term plan to pay within 180 days,
a long-term installment agreement,
Currently Not Collectible status if you truly can't pay right now, or
in some cases, an Offer in Compromise.
Can the penalties be removed? IRS penalty relief
Sometimes. The main routes:
Reasonable cause. If you acted in good faith and something outside your control kept you from filing or paying, like a serious illness or a disaster, you can ask the IRS to remove the penalty.
First Time Abate. If you have three years of clean compliance history, the IRS may remove failure-to-file, failure-to-pay and failure-to-deposit penalties for one period. You have to ask.
Automatic Exemption from Penalty (new). Starting in summer 2026, the IRS is phasing in an automatic version of this relief, starting with 2025 tax year returns. If you qualify, the penalty isn't assessed at all. Not every return type is covered, so check the notice you get.
When a penalty is removed, the interest on that penalty comes off too.
FAQ
Should I file my tax return if I can't pay?
Yes. The failure-to-file penalty is generally 5% a month, compared with 0.5% a month for paying late. Filing stops the bigger penalty from growing.
What is the maximum failure-to-file penalty?
Generally 25% of the unpaid tax. If you're more than 60 days late, there's also a minimum penalty.
Does a payment plan reduce penalties?
For individuals who filed on time, the failure-to-pay penalty drops to 0.25% a month while an approved payment plan is in place.
Can I get IRS penalties removed?
Possibly, through reasonable cause, First Time Abate, or the new automatic relief if you qualify.
Does an extension help if I can't pay?
It gives you more time to file, not to pay. Interest and the late-payment penalty still run on unpaid tax, but a valid extension keeps the bigger late-filing penalty off.
Related: IRS payment plan vs. a loan · NY, NJ & CT tax penalty abatement · Unfiled tax returns help
Official sources: IRS: Failure to file penalty · IRS: Failure to pay penalty · IRS: Penalty relief
Behind on filing, or staring at a penalty notice?
Book a free consultation to go over your case. I'll tell you honestly what I see.
Every case is different.
Solomon Grosinger, Enrolled Agent
I'm licensed by the IRS and have represented taxpayers before the IRS and New York, New Jersey, Connecticut and Pennsylvania tax agencies from Brooklyn since 2017.
General info, not advice for your specific case.