IRS lien vs. levy: a lien is a claim on your property, a levy takes the money from a bank or paycheck
A client called me in a panic over IRS action.
Here's the IRS lien vs. levy difference in plain words.
A few weeks earlier, I had arranged a short-term payment plan for his business. The business owed a significant amount, and part of it was trust fund recovery liability. They weren't approved for a long-term installment agreement, so they chose to pay very large sums every week to bring the balance down fast.
Then they applied for a business loan and got declined. The reason: the IRS had a lien against all of their assets.
He was furious. He was already making big payments, and a lien was still sitting on everything. His question to me was fair: what did the payment arrangement accomplish if the lien is still there?
Here's what I told him
The win wasn't "no lien." The win was that the IRS didn't levy his bank account.
With a levy, the bank freezes the account and then sends the money to the IRS. For a business, that can mean no payroll, no rent and no supplier payments. It can shut a company down overnight.
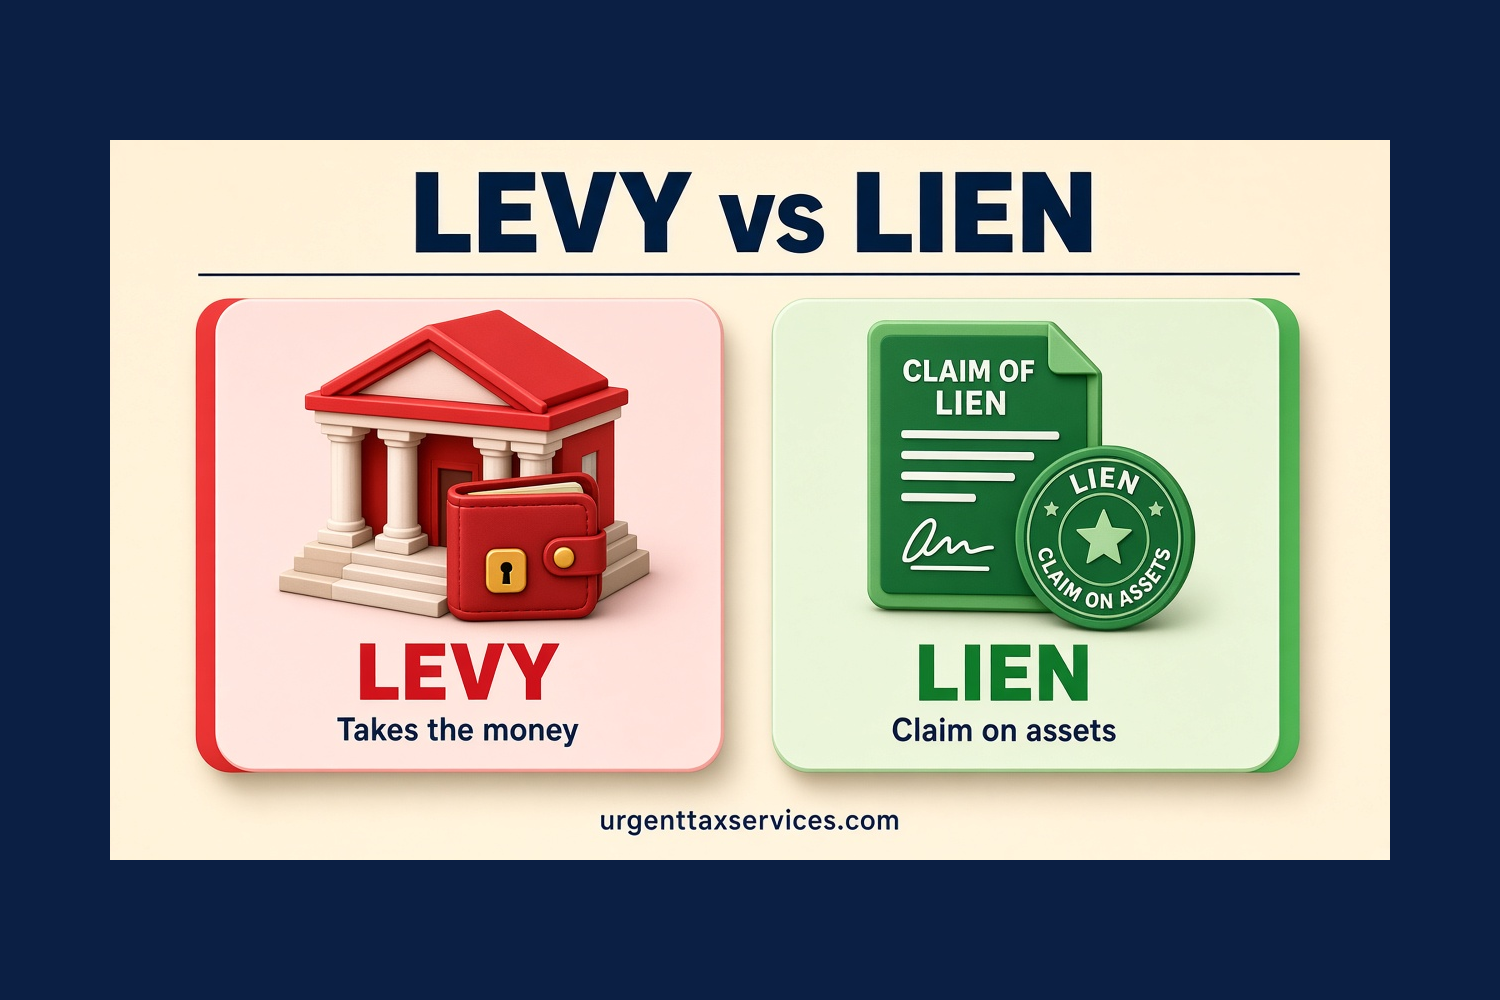
A lien and a levy are not the same thing. One is a claim against your property. The other is the IRS actually taking it.
What a federal tax lien is
A federal tax lien is the government's legal claim against your property when a tax debt isn't paid. It arises after the IRS assesses the tax, sends you a bill, and the bill isn't paid in full.
The IRS can also file a public Notice of Federal Tax Lien. That notice tells creditors the government has a claim. It attaches to everything: real estate, vehicles, bank accounts, business property, even accounts receivable. And it can make it much harder to get credit. That's exactly what my client ran into.
What an IRS levy is
A levy is the IRS legally seizing property to pay the debt. It can hit:
your bank account (frozen, then sent to the IRS after a 21-day waiting period),
your wages (a continuous levy, every paycheck),
and other property in some cases.
The IRS generally has to send a final notice of intent to levy and offer you a hearing before most levies. That's why those letters matter so much.
How do you get rid of a lien?
Paying the debt in full is the most direct way. The IRS releases the lien within 30 days after the debt is paid.
There are other tools when they fit the facts:
Discharge removes the lien from a specific property, for example to allow a sale.
Subordination lets another lender move ahead of the IRS, which can help with a loan or refinance.
Withdrawal removes the public notice. You still owe the money. In some cases, a withdrawal is possible if you're on a direct debit installment agreement and meet the IRS's conditions.
Each of these has rules, and not everyone qualifies. Some can take time.
The point
When you owe the IRS, it's easy to focus on the thing that feels unfair, like the lien. But stopping the levy is often the thing that keeps you in business. A payment arrangement that keeps your bank account open can be a real win, even when the lien is still there.
Then, step by step, we work on the lien too.
FAQ
Does a payment plan remove an IRS lien?
Not by itself. The lien generally stays until the debt is paid, unless you qualify for a withdrawal, discharge or subordination.
Can the IRS levy without warning?
In most cases, the IRS must first send a final notice of intent to levy and give you a chance to request a hearing. There are some exceptions.
Will a lien hurt my ability to borrow?
It can. A filed Notice of Federal Tax Lien may limit your ability to get credit.
Is a state tax warrant like a federal lien?
In New York, a tax warrant is equivalent to a civil judgment and creates a lien on your property. So yes, it works in a similar way.
Can the IRS levy my bank account?
Yes, generally after the final notice of intent to levy and your chance to request a hearing. The bank holds the funds for 21 days before sending them to the IRS.
Related: CP504 vs. LT11 · No IRS lien filed? Why it still counts · IRS bank levy help · The IRS needs a boss’s signature before it can penalize you
If a filed lien is blocking a sale or refinance in Brooklyn or NYC, start with IRS tax lien help.
Official sources: IRS: Understanding a federal tax lien · IRS: What is a levy? · IRS: Information about bank levies
Got an IRS or state notice?
Book a free consultation to go over your case. I'll tell you straight where you stand.
Every case is different.
Solomon Grosinger, Enrolled Agent
I'm licensed by the IRS and have represented taxpayers before the IRS and New York, New Jersey, Connecticut and Pennsylvania tax agencies from Brooklyn since 2017.
General info, not advice for your specific case.