No IRS lien filed? Why it’s as if it’s filed
"The IRS never filed a lien against me. So I'm fine, right?"
Clients ask me some version of this all the time. Here's what I tell them every day:
"Even if the IRS doesn't file a lien, it's as if it's filed."
Between you and the IRS, that's the law. There's one real limit, and I'll get to it. But first, here's where the lien comes from.
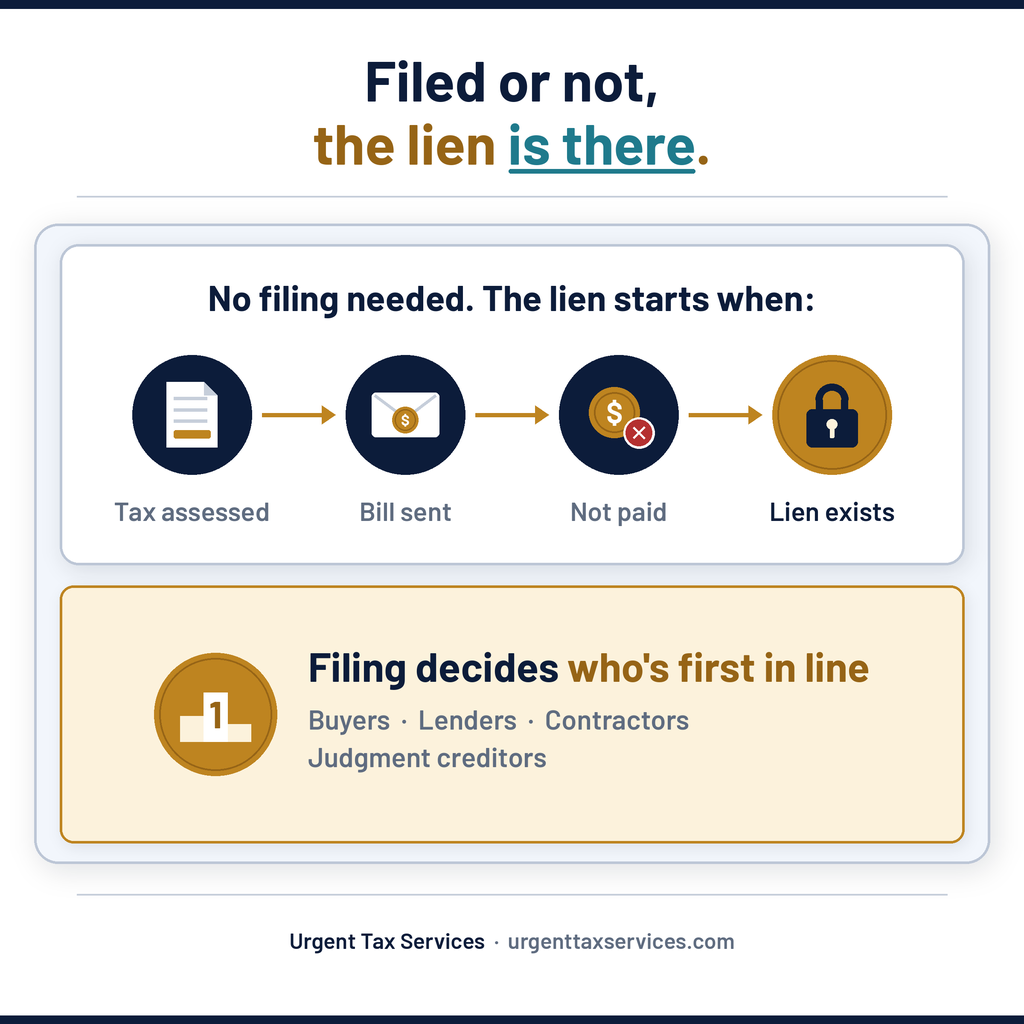
The lien starts without any paperwork
Section 6321 of the tax code creates the federal tax lien. It happens in three steps:
The IRS assesses the tax, meaning it puts the balance on its books.
It sends you a bill (a notice and demand for payment).
You don't pay it in full.
That's it. The lien exists, and under Section 6322 it's treated as starting on the date of the assessment. It covers the tax, penalties and interest. Nobody has to record anything. That's why it's sometimes called the "secret lien."
The Notice of Federal Tax Lien is a separate, later step. It's the public announcement. The IRS generally files one when you owe $10,000 or more, though it can file for less. When it does, it has to send you a letter within 5 business days, and you get 30 days after that to ask for a hearing with the IRS Independent Office of Appeals.
7 ways an unfiled lien still bites
1. The IRS can levy without ever filing a lien. A levy on your bank account or wages doesn't depend on a filed notice. The IRS generally has to send a final notice of intent to levy and offer you a hearing first, but a filed lien isn't a requirement.
2. It covers property you get later. The lien attaches to everything you own while it lasts, including property you acquire after it arises. The Supreme Court said so back in 1945, and the IRS regulations say it plainly. Buy a house next year, and the lien attaches the moment you own it.
3. You can't refuse an inheritance to dodge it. In Drye v. United States (1999), a man who owed the IRS about $325,000 disclaimed his mother's estate so it would pass to his daughter. State law said his creditors couldn't touch disclaimed property. The Supreme Court said the federal lien attached anyway, because he had the power to decide who got the money.
4. It reaches a home you own with your spouse. In New York, a home deeded to a married couple is usually owned as tenants by the entirety. Many people think that shields the house when only one spouse owes. In United States v. Craft (2002), the Supreme Court held that the federal lien attaches to the owing spouse's interest. In some cases, the IRS can ask a federal court to order a sale of the whole home, with the other spouse paid for their share. Courts weigh the hardship before allowing that. (If you filed jointly, the debt may be both of yours anyway.)
5. It reaches money owed to you. Customer receivables, payments due under a contract, installment payments from a property you sold. These are "rights to property," and the lien covers them. A joint bank account you can withdraw from is fair game too. The co-owner can try to prove the money is theirs, but that fight comes after the levy.
6. Selling or refinancing doesn't wash it out. The cash you walk away with is your property, so the lien is on it. And the IRS can file the notice any day, including the week before your closing. Once it's filed, the title search will usually find it, and the deal waits on a payoff, a release, or a discharge.
7. Giving property away doesn't shake it off. The law protects a buyer who pays full value. A relative who gets the house as a gift isn't that buyer, so the lien generally follows the property. The IRS can also file a lien naming the relative as your "nominee," or go after them as a transferee.
And it lasts. The lien runs for the collection period, generally 10 years from the assessment, filed or not. Some events, like a pending offer in compromise or a bankruptcy, can extend that.
Separately, the IRS will apply your future tax refunds to the balance. That's a different rule, but it's one more thing that happens without any filed lien.
The honest limit: what filing actually changes
Here's where "as if it's filed" stops. Under Section 6323(a), an unfiled lien isn't valid against four groups:
a buyer who pays for the property,
a lender holding a mortgage or other security interest,
a contractor with a mechanic's lien, and
a creditor with a court judgment.
So if you sell your building before the IRS files, the buyer takes it free of the lien. If a bank records its mortgage first, the bank comes ahead of the IRS. Filing is about priority. It decides who's first in line against those outsiders.
That's also why the place of filing matters. New York law sets the offices. If you live in Brooklyn, a notice against your home or your personal property is filed with the City Register. In Rockland or Westchester, it's the county clerk. For a corporation or partnership's personal property, it's the New York Department of State. A notice filed in the wrong office may not hold the IRS's place in line against those four groups.
Even a filed lien has a few exceptions. Someone who buys your car without knowing about the lien and takes possession, or a shopper buying from your store's inventory in the normal course of business, can take free of it. Local property taxes on real estate can also come ahead of the IRS.
What I'd do if you owe and nothing has been filed yet
Treat it as a window, not a pass. You have more options now than after a filing or a levy.
Get the real numbers. Pull your IRS account transcripts to see the balance, the assessment dates and how much time is left on the collection period.
Look at the $10,000 line. If you're near it, paying down the balance or setting up a payment plan early can matter.
Don't move property to family. It usually doesn't work, and it can make things worse.
Plan sales and refinances ahead. Don't find out about a lien at the closing table.
Watch the mail. If a lien filing letter comes, the 30-day hearing window is short.
If you can't pay in full, an installment agreement or an offer in compromise may fit. Each has trade-offs.
Short FAQ
Is there an IRS lien if no notice was filed? Yes. The lien arises once the tax is assessed, you're billed, and you don't pay. The filed notice only makes it public and sets priority against certain creditors.
Does an IRS lien show up on my credit report? Not on your personal credit report. The three big credit bureaus stopped reporting tax liens in April 2018. But lenders and title companies search public records, so a filed notice still comes up.
Will the lien attach to a house I buy later? Yes. It attaches to property you acquire while the lien lasts.
My spouse owes the IRS, not me. Can the lien touch our house? It can attach to your spouse's interest, even in a home owned as tenants by the entirety. What happens next depends on the facts.
General info, not advice for your specific case.
Worried about an IRS lien, filed or not?
Book a free 30-minute call to go over your case. For a quick question, you can call (718) 510-3166. I'll tell you honestly where you stand.